Buying guide
Home renovation loans: How to get one + how they work
Let’s finance those renos

AI summary
Financing a renovation? A mortgage top-up is often the best choice, adding to your existing home loan at lower interest rates. This usually requires a fixed-price contract and limits borrowing to 80% of your home's 'as complete' value.
Alternatively, a personal renovation loan is an option if you lack equity. However, these come with significant drawbacks:
- Much higher interest rates
- Shorter loan terms
- Lower borrowing limits
Always explore all funding options before committing to high-interest debt.
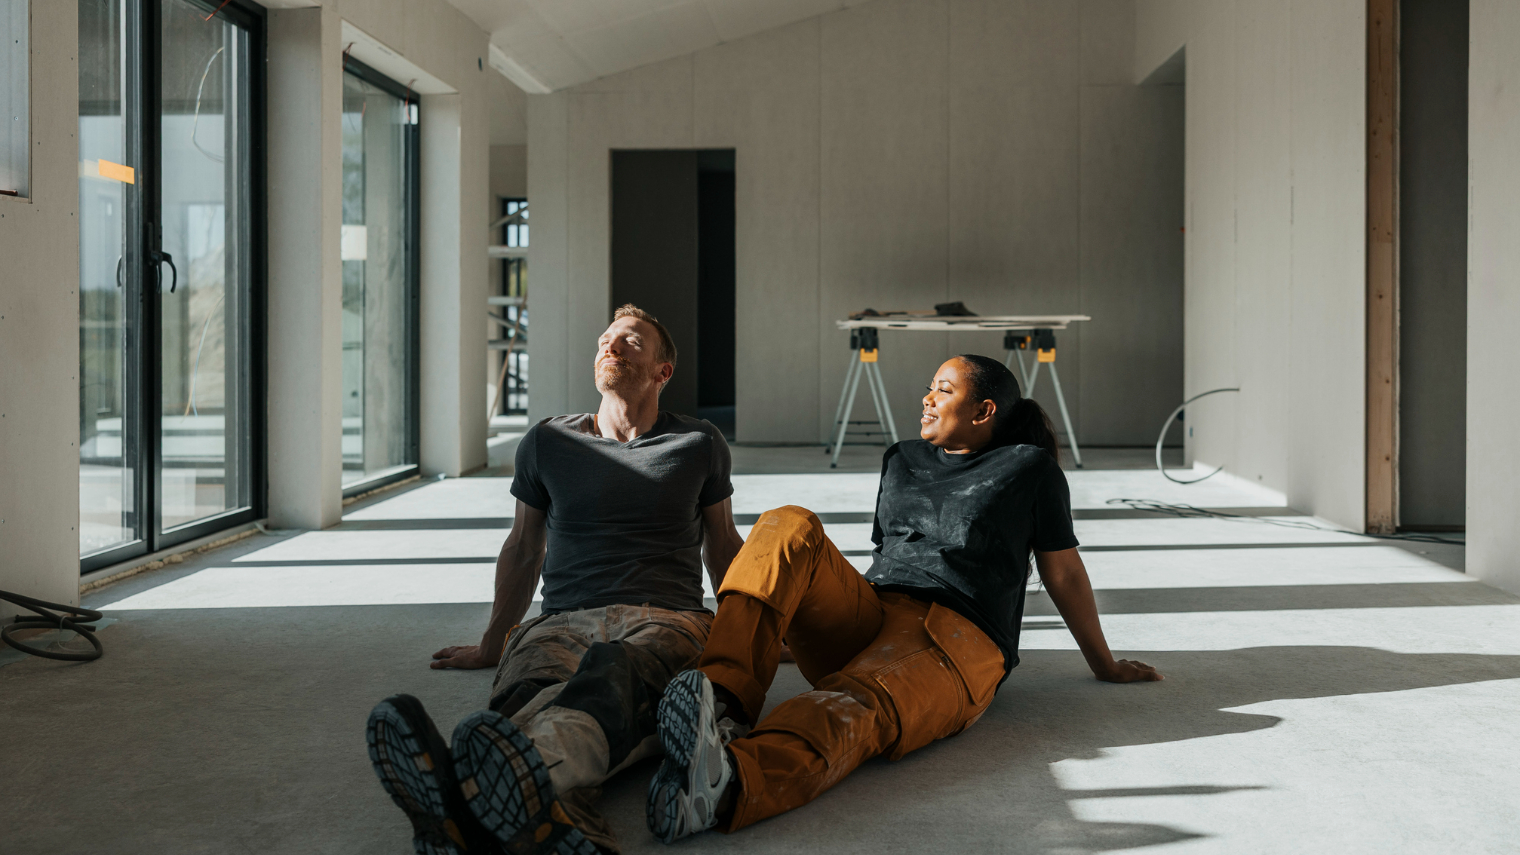
For many people a mortgage top up is the best option
Can’t borrow against your home? Consider a renovation loan
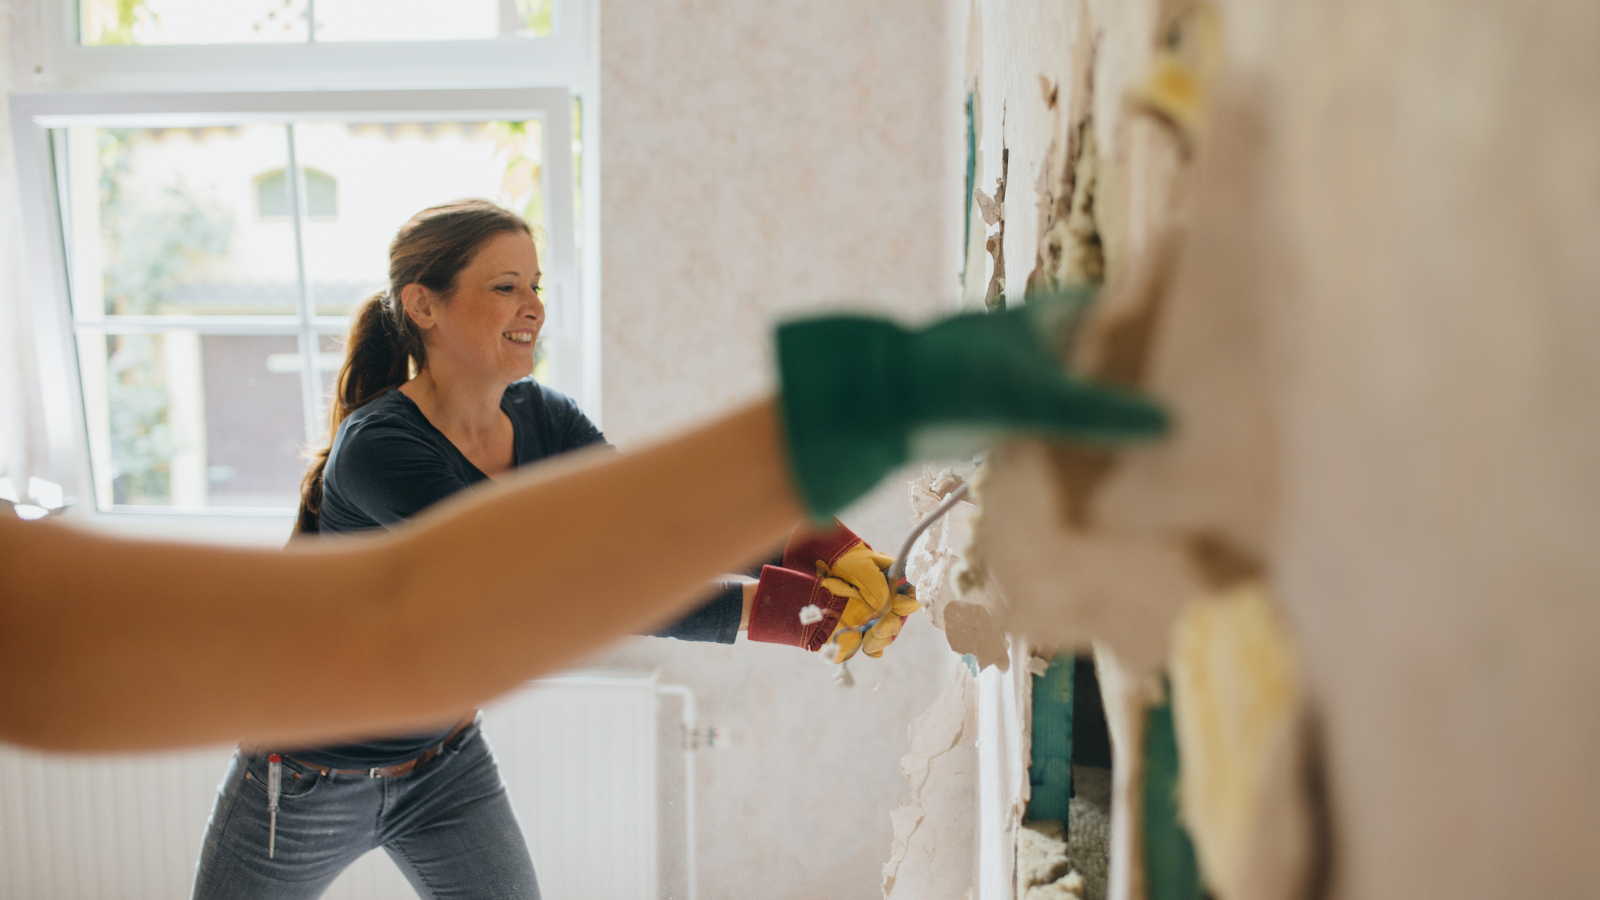
Before you start knocking down walls make sure your finance is sorted.
Drawbacks of renovation loans (there are a few)
ALWAYS APPROACH WITH CAUTION
How to keep your renovation budget down
Author
Discover More
Coast to Coast founder went for a walk one morning in his pyjamas. He came home having bought a house
Robin Judkins bought a rundown Sumner home on a whim and transformed it into a creative retreat.
Four ovens, multiple fridges and a 13-metre wall: Inside NZ’s best new kitchen
Explore NZ’s award-winning Te Arai kitchen, with a sculptural island and 13m wall of oak joinery.


Search
Other articles you might like